Banks in UAE: A Guide to Choosing the Right Bank
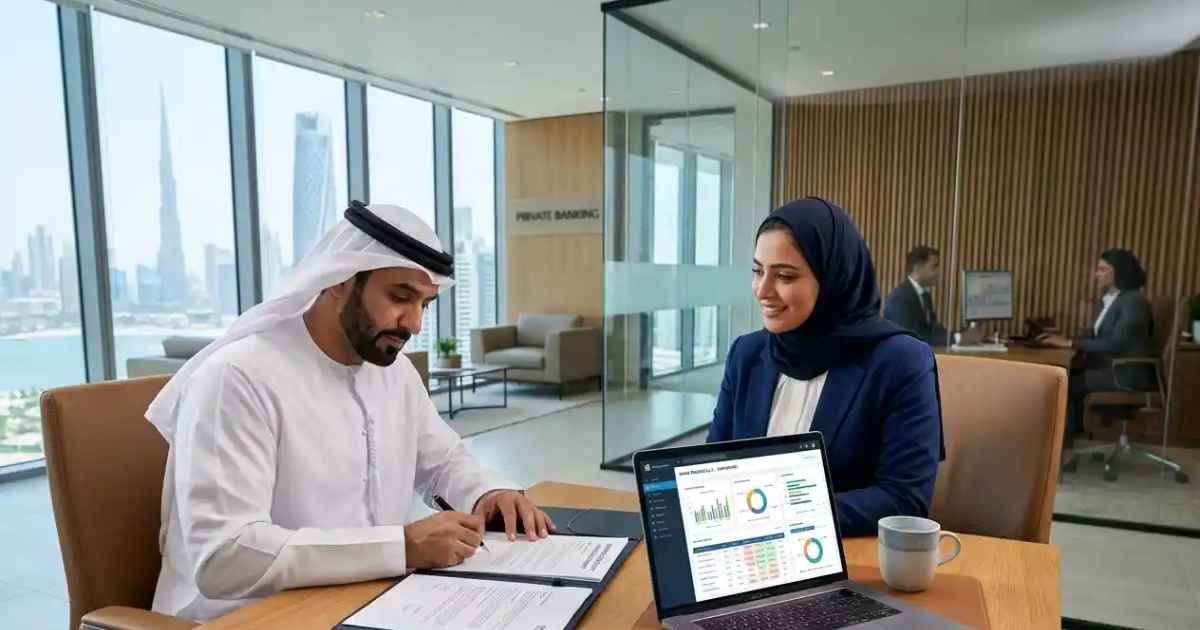
Choosing among the banks in the UAE can feel overwhelming because customers have access to a wide range of traditional banks, digital banking services, Islamic banks, and international financial institutions. Each bank may offer different account types, fees, credit cards, financing options, digital services, and investment products.
The right bank depends on your individual financial needs. Someone looking for a simple salary account may have very different priorities from a business owner, frequent traveller, investor, or customer looking for Shariah-compliant banking.
This guide explains what to consider when comparing banks in the UAE.
Understanding the UAE Banking Sector
The UAE has a developed banking sector serving individuals, businesses, investors, and international customers.
Broadly, customers can encounter:
- Conventional banks
- Islamic banks
- Digital banks
- Local banks
- International banks
- Retail and corporate banking providers
Banks may offer services including:
- Current accounts
- Savings accounts
- Fixed deposits
- Credit cards
- Personal finance
- Home finance
- Business banking
- Investment services
- Foreign currency services
The products available depend on the individual institution.
What Should You Look For in a UAE Bank?
Before opening an account, consider your main financial requirements.
1. Account Types
First, check whether the bank offers the type of account you need.
Common options include:
- Current accounts
- Savings accounts
- Salary accounts
- Zero-balance accounts
- Fixed deposits
- Foreign-currency accounts
If you are primarily interested in saving, compare savings and deposit products rather than choosing a bank based only on its popularity.
2. Minimum Balance Requirements
Some bank accounts require customers to maintain a minimum balance.
If the balance falls below the required amount, a monthly fee may apply.
A bank offering a zero-balance or low-balance account may be more suitable if your savings fluctuate regularly.
Always check the specific account terms because requirements can differ within the same bank.
3. Interest or Profit Rates
If earning a return on savings is important, compare the available rates.
Conventional savings accounts may offer interest, while Islamic banking products may use profit-based structures.
When comparing rates, check:
- Applicable balance
- Promotional period
- Minimum deposit
- Maximum qualifying balance
- Payment frequency
- Eligibility conditions
A high advertised rate may apply only to a specific portion of your savings.
4. Fees and Charges
Banking fees can significantly affect the overall value of an account.
Potential charges include:
- Account maintenance fees
- Minimum-balance fees
- ATM fees
- Transfer fees
- Debit card fees
- International transaction fees
- Foreign exchange charges
- Cheque-related charges
Before opening an account, review the bank’s latest fee schedule.
5. Digital Banking Services
A reliable mobile app and online banking platform can make everyday banking much easier.
Useful features may include:
- Mobile transfers
- Bill payments
- Card controls
- Instant notifications
- Digital statements
- Account management
- Money transfers
- Cheque or document services
If you prefer to manage finances online, compare the digital experience carefully.
6. ATM and Branch Network
For customers who regularly use cash or prefer face-to-face service, branch and ATM availability matters.
Consider:
- Number of branches
- ATM availability
- Locations near your home or workplace
- Cash deposit facilities
- Operating hours
- International ATM access
Digital banking may reduce the need for branches, but physical access can still be useful.
7. Salary Account Requirements
Many banks in uae employees receive their salary through a bank account.
Some banks offer special benefits for customers who transfer their salary, such as:
- Lower fees
- Special savings rates
- Credit card offers
- Financing options
- Other banking benefits
Check whether the account requires a minimum salary and whether benefits depend on continued salary transfer.
Conventional vs Islamic Banks
One of the key choices for customers in the UAE is between conventional and Islamic banking.
Conventional Banking
Conventional banks generally operate using interest-based financial products.
They may offer:
- Savings accounts
- Fixed deposits
- Credit cards
- Loans
- Mortgages
- Investment services
Islamic Banking
Islamic banks follow Shariah-compliant financial principles.
Depending on the product, structures may involve concepts such as profit-sharing or asset-based financing rather than conventional interest.
If Shariah compliance is important to you, review the specific product documentation and the bank’s official information.
Savings Accounts at UAE Banks
If your main goal is saving money, compare the savings accounts offered by different banks.
Important factors include:
- Interest or profit rate
- Minimum balance
- Maximum eligible balance
- Monthly fees
- Withdrawal restrictions
- Promotional conditions
Do not assume that the bank with the highest advertised rate is automatically the best choice.
Fixed Deposits
Fixed deposits may be suitable for customers who have money they do not need immediately.
A fixed deposit typically locks money for a predetermined period in exchange for an agreed rate, subject to the product’s terms.
When comparing fixed deposits, consider:
- Deposit rate
- Tenure
- Minimum deposit
- Early withdrawal conditions
- Maturity instructions
- Renewal rate
Credit Cards
UAE banks offer many types of credit cards.
Depending on the card, benefits may include:
- Cashback
- Reward points
- Air miles
- Travel benefits
- Dining discounts
- Airport-related benefits
However, compare the full cost of the card, including annual fees and other charges.
A rewards card is generally more useful when the benefits outweigh its costs and you can manage repayments responsibly.
Personal Finance and Home Finance
Customers may also compare banks based on financing options.
For personal or home finance, consider:
- Interest or profit rate
- Fees
- Repayment period
- Early settlement conditions
- Eligibility requirements
- Total cost of financing
Do not compare financing products based only on the advertised monthly payment.
Banking for Expats in the UAE
The UAE has a large expatriate population, and banks offer accounts designed for different customer profiles.
Depending on your residency and employment status, a bank may request:
- Passport
- Emirates ID
- Residency documentation
- Salary certificate
- Employment information
- Proof of address
Requirements vary between banks and account types.
Non-residents can face different eligibility rules, so always check directly with the bank.
Business Banking
If you own or operate a business in the UAE, your banking requirements may differ from those of an individual.
Business customers may need:
- Corporate accounts
- Business debit cards
- Merchant services
- Payroll solutions
- Business financing
- International transfers
- Cash-management services
Compare banks based on the services your business actually requires.
International Banking Services
For people who regularly send or receive money internationally, foreign exchange and transfer services are particularly important.
Compare:
- Supported currencies
- Transfer fees
- Exchange rates
- Transfer limits
- Processing times
- International payment options
A bank with a convenient international transfer service may be more suitable for frequent cross-border transactions.
Customer Service
Good customer support can make a significant difference.
Before choosing a bank, consider whether it offers:
- Telephone support
- Live chat
- Email support
- Branch assistance
- Mobile-app support
- Multilingual services
Also consider how easy it is to resolve account or card issues.
How to Compare Banks in the UAE
A simple comparison table can help:
| Feature | Bank A | Bank B | Bank C |
| Savings account | ✓ | ✓ | ✓ |
| Zero-balance option | Check | Check | Check |
| Fixed deposits | ✓ | ✓ | ✓ |
| Mobile banking | ✓ | ✓ | ✓ |
| Branch access | Compare | Compare | Compare |
| Minimum balance | Compare | Compare | Compare |
| Fees | Compare | Compare | Compare |
| Credit cards | ✓ | ✓ | ✓ |
| International transfers | ✓ | ✓ | ✓ |
The best bank will depend on which features are most important to you.
Common Mistakes When Choosing a Bank
Choosing Based Only on Brand Name
A well-known bank may not have the account features that suit your needs.
Ignoring Fees
Small recurring charges can add up over time.
Focusing Only on Promotional Rates
Promotional savings rates or credit card offers may have limited durations.
Not Checking Eligibility
Some accounts require specific salary levels, residency status, or other criteria.
Ignoring Digital Banking
If you primarily bank through your phone, the quality of the mobile app can be important.
Not Comparing International Transfer Costs
Frequent international transfers can make exchange rates and fees a major consideration.
Questions to Ask Before Opening an Account
Before choosing a bank in the UAE, ask:
- What account types are available?
- Is there a minimum balance requirement?
- What fees apply?
- What savings interest or profit rates are available?
- Are promotional rates subject to conditions?
- Is salary transfer required?
- How good is the mobile banking service?
- Where are the nearest branches and ATMs?
- What international transfer options are available?
- What documents are required?
- Are Islamic banking products available?
- What customer support options are offered?
How to Choose the Right UAE Bank
Start with your primary financial goal.
If you need an everyday account, focus on fees, ATM access, digital banking, and transaction convenience.
If you are primarily saving, compare interest or profit rates, balance requirements, and withdrawal flexibility.
If you travel frequently, consider international transactions, foreign exchange costs, and travel-related card benefits.
If you run a business, prioritise business banking services, payment solutions, financing, and international transfers.
There is no single bank that is best for every customer.
Conclusion
The wide range of banks in the UAE gives customers plenty of choices, but it also makes comparison important. The right bank should match your financial goals, spending habits, savings needs, and preferred banking services.
Before opening an account, compare account types, minimum balances, fees, interest or profit rates, digital banking features, ATM and branch access, salary requirements, international services, and customer support.
If you are considering credit cards, financing, or investment products, compare those separately rather than assuming that the same bank will offer the best deal for every financial need.
Disclaimer: The information provided in this article is for general informational and educational purposes only. It does not constitute financial, banking, or investment advice. Bank products, fees, eligibility, and rates change frequently; readers should verify all details directly with the relevant bank before opening an account. The author and publisher disclaim all liability for any financial losses or outcomes arising from reliance on this content. Always consider your personal financial situation and conduct your own research before making banking decisions. This article does not endorse any specific bank or product.
Uncover the methods that drive excellence—our excellence frameworks set the gold standard.